
Instant Cash Advance Loan App
- Rating
- 4.6
- Downloads
- 1.00M
- Content Rating
- Everyone
Instant Cash Advance Loan App - Screenshots
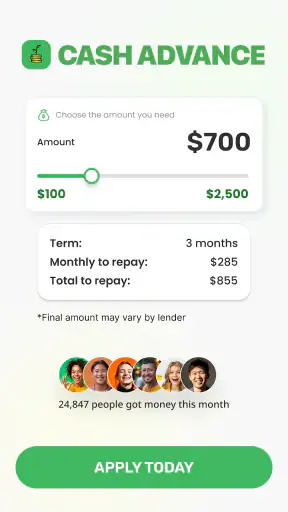
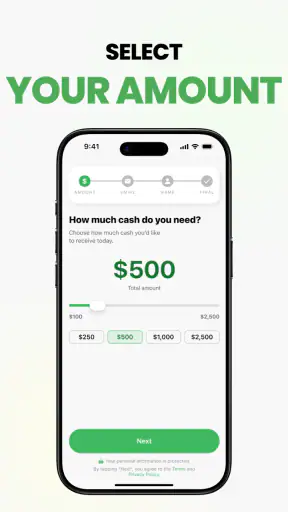
Pros
- Fast application process with minimal paperwork
- Clear repayment schedule shown before accepting an offer
- Useful for covering unexpected short-term expenses
- Loan options may be available outside standard banking hours
- Mobile access makes account management convenient
Cons
- Interest and service fees can make borrowing expensive
- Approval and loan amounts vary by applicant and location
- Late payments may trigger additional fees or affect credit
- Some features may require sharing sensitive financial information
- Short repayment periods can make installments difficult to manage
Instant Cash Advance Loan App - Description
- App Name
- Instant Cash Advance Loan App
- Package Name
- com.instant.cash.advance.loan.app
- Developer
- Fast Online Loans
- Category
- Finance
- Last Updated
- Aug 15, 2021
- Version
- 2.0.9
When an unexpected bill arrives between paydays, the appeal of a cash advance app is obvious: I want a clear way to understand my options without spending an afternoon searching through unrelated financial products. Instant Cash Advance Loan App is built around that immediate need. It is a free finance app from Fast Online Loans, and its purpose is much narrower than a budgeting suite or a traditional banking app. It focuses on helping users explore short-term borrowing rather than managing every part of their financial life.
My first impression is that the app makes sense for a very specific moment: I have a temporary cash gap, I understand that borrowing has a cost, and I need to review an option quickly. That does not automatically make it the right answer. A loan application is a financial decision, not just another download, so the useful question is not whether the app feels fast. It is whether the convenience remains worthwhile after I consider repayment, eligibility, privacy, and the alternatives available to me.
What the first week feels like
The first-week appeal comes from the app’s focused purpose. Instead of asking me to learn a large financial dashboard, it presents itself as a cash advance app for people looking into short-term funds. That narrow scope can be helpful when I am under time pressure. I am not opening it to track investments or build a long-term savings plan; I am opening it because I need to investigate a borrowing possibility.
The app is listed as free, which removes the usual download barrier. That should not be confused with a free loan. The cost of borrowing depends on the offer, terms, and repayment obligations presented during the process, so I would treat the app as a way to begin evaluating a financial product rather than as money that arrives without conditions. This distinction is easy to miss when an app’s name emphasizes speed.
During an initial session, I would keep my goal modest: understand what information is requested, see whether the process is relevant to my situation, and read every repayment detail before continuing. I would not rush through screens simply because the product is designed around urgency. A short pause to check the total repayment amount, due date, and any applicable charges is more valuable than saving a few minutes at the start.
The app is aimed at a broad audience, with an Everyone content rating, but that label is not financial advice and does not mean every adult should borrow. Age suitability and credit suitability are different questions. Someone can be allowed to view the app and still be in a poor position to take on another payment. I find this distinction especially important for younger users who may interpret an accessible interface as a sign that approval or repayment will be easy.
Instant Cash Advance Loan App has reached over a million installs and carries a 4.6 average from around 52 thousand ratings. Those figures suggest that the concept has connected with a substantial audience, but popularity cannot tell me whether a particular offer is affordable. I would use the app’s reach as a reason to examine it, not as proof that borrowing through it is suitable for me.
A realistic emergency use case
Imagine that my car needs an urgent repair just before payday, and I need transportation to keep working. I could open the app to investigate whether a short-term loan is available, but I would compare that option with asking the repair shop about a payment arrangement, contacting my bank, checking an employer advance, or using an existing emergency fund. The app is useful in this scenario because it puts one possible route in front of me quickly. It is not useful if it encourages me to stop comparing after the first available option.
That is one of the less obvious trade-offs: speed can improve access to information while also reducing the time I spend questioning the decision. I would write down the amount I actually need before opening the application. If I start by browsing the maximum amount offered, I may borrow more than the repair requires. Defining the need first keeps the tool in its proper role: helping me solve a specific shortfall, not expanding the shortfall.
I would also decide in advance how repayment would fit into my next income cycle. If the payment would force me to borrow again for groceries, rent, utilities, or transportation, the app is not solving a temporary problem. It is moving the problem forward. That is a practical test I would apply before submitting any information, and it matters more than how polished or quick the first session feels.
What to check before moving forward
A careful first-week workflow is more valuable than simply completing an application. I would check the amount requested, the total amount to repay, the repayment date, the consequences of missing that date, and whether the arrangement fits my actual income schedule. I would also read the privacy and authorization screens rather than tapping through them automatically. Financial apps handle sensitive information, so convenience should never replace attention.
Another useful habit is to save my own notes outside the app. I would record the offer details and the date I reviewed them, because relying on memory is risky when several financial options look similar. If the app sends me elsewhere to complete a lender process, I would confirm that I understand who is making the offer and who I would owe. A recognizable app name does not eliminate the need to identify the actual financial obligation.
The current version is 2.0.9 and it supports Android 7.0 or later. That makes it accessible on many older Android phones, which can matter for people who cannot replace a device every year. At the same time, compatibility should not be mistaken for a guarantee that every handset will provide the same experience. I would keep the operating system updated where possible and install only through a trusted app marketplace.
Does it earn a place month after month?
For long-term value, this app faces a difficult test. A cash advance tool is not naturally a daily habit for most people, and I would not want it to become one. Its recurring value comes from being available when I need to review a short-term borrowing option, not from encouraging repeated borrowing. That means the app may be useful to keep available without being something I open every morning.
Once the immediate emergency is over, I would expect its value to decline unless I am actively comparing a new, clearly understood need. A budgeting app may earn a permanent place because it helps me monitor spending and plan ahead. A bank app may remain essential because it manages accounts and payments. This loan-focused app has a narrower job, so it should be judged by whether that job is performed clearly and responsibly when required.
The strongest recurring use is as a reference point during a financial comparison. I might review the borrowing route, then compare it with a credit union, a bank, an employer-based advance, a payment plan, or help from a trusted person. Even when I do not use the loan, the app can help me clarify what information lenders request and what repayment commitment I would be considering. That is a more sustainable role than treating it as a standing source of extra spending money.
I would not recommend checking the app repeatedly just to see whether I can access more funds. That behavior can turn an occasional tool into a source of financial pressure. If I have already borrowed, I would focus on the repayment plan rather than browsing for another advance. The app’s lasting value depends partly on my discipline: it can support a decision, but it cannot create room in a budget that does not have any.
How it compares with familiar alternatives
Compared with a traditional bank or credit union, a dedicated cash advance app may feel more direct and less intimidating for someone seeking a small, short-term solution. A bank relationship may offer broader services and a more complete view of my finances, while a credit union may provide personal guidance or different lending terms depending on membership and eligibility. I would compare the total cost and repayment flexibility rather than choosing based only on which interface seems faster.
Compared with borrowing from a friend or family member, the app offers a formal process but may create a financial obligation that is less flexible than an informal arrangement. Compared with an employer advance, it may be available independently of workplace policies, but an employer option could avoid some borrowing costs. Compared with a credit card, it may serve a different purpose, yet a card’s interest, fees, and repayment structure also need careful review. There is no universal winner here; the right choice depends on the amount, urgency, and certainty of repayment.
A budgeting app is a different kind of alternative. It will not necessarily solve an immediate shortfall, but it can reveal whether the emergency is part of a repeating pattern. If I need a cash advance every month, I would get more lasting benefit from tracking income, fixed bills, variable spending, and upcoming irregular expenses. In that situation, this loan app may be a symptom-management tool when what I really need is a plan to reduce the recurring gap.
That comparison also explains why I would not keep this app at the center of my financial routine. It can be practical for a narrow event, but it does not replace an emergency fund, a spending plan, or personal advice. Its best use is temporary and deliberate. If a different option is cheaper, more flexible, or easier to understand, I would choose that option even if this app is quicker to open.
The maintenance burden after installation
The maintenance burden is not mainly about storage space or frequent interaction. It is about keeping my financial information and expectations under control. I would review whether I still need the app after the emergency has passed, avoid leaving unnecessary financial applications on a shared or unsecured device, and check that I understand any notifications rather than treating them as invitations to borrow.
Because the app is designed around loans, I would be especially careful with permissions, account details, and personal identification information. I would grant only what is necessary for the process I intend to use and read the explanation attached to each request. If a screen feels unclear, I would stop and investigate before continuing. That pause is not friction to eliminate; in a financial app, it is a useful safety step.
Updates can improve compatibility and reliability, but I would still read changes that affect the application process or information handling. The developer is Fast Online Loans, and the app’s current version is 2.0.9. Those details help identify the product I am using, but they do not remove my responsibility to review the terms shown at the time of borrowing. Financial conditions can matter far more than the version number.
I would also maintain a separate repayment reminder in my calendar or banking system. Depending on one app to remind me about an obligation is not a strong workflow, particularly if I change phones, lose access, or stop using the app. A second reminder gives me a clearer view of the payment alongside rent, utilities, and other commitments. This is a small practical improvement that can prevent a short-term decision from becoming a late-payment problem.
Where the experience can become tiring
The main source of fatigue is the gap between fast access and careful evaluation. A user may arrive needing money immediately, while the responsible process requires reading terms, comparing alternatives, confirming repayment capacity, and protecting personal information. That tension is built into the category, and no streamlined interface can remove it completely.
I would also find repeated borrowing mentally expensive even when each individual session appears simple. The more often I use an advance to cover ordinary expenses, the harder it becomes to tell whether I am handling an emergency or postponing a budget problem. The app may remain easy to open, but the financial consequences can become increasingly difficult to manage.
Another possible frustration is that a user may expect the app’s name to guarantee an instant result. I would not make that assumption. A loan inquiry can involve eligibility checks, information requests, and terms that need review. The useful outcome of a session might be discovering that the option is unsuitable, not receiving money. Treating that conclusion as a success protects me from forcing a poor decision simply because I started the process.
The free download can also create the wrong mental shortcut. I would remind myself that the app’s price and the loan’s cost are separate matters. Downloading it costs nothing, but borrowing can affect my future budget. Keeping those ideas separate is one of the simplest ways to avoid confusing app convenience with financial affordability.
My long-term verdict
After the novelty fades, Instant Cash Advance Loan App earns a limited but legitimate place for users who occasionally need to investigate short-term borrowing and are prepared to compare the result carefully. I like its focused purpose, broad Android compatibility, and accessible entry point. Its strong user response, with more than two thousand written reviews alongside its 4.6 average, indicates that many people find the concept useful. Still, those signals do not change the central question: can I repay the obligation without creating another emergency?
I would recommend it to someone facing a genuine, temporary cash gap who wants to examine one route quickly, provided that person reads every term and checks cheaper or more flexible alternatives first. I would not recommend it as a routine income supplement, a substitute for budgeting, or a way to fund discretionary purchases. Anyone already juggling several debts should be particularly cautious and may be better served by speaking with a bank, credit union, nonprofit adviser, or trusted financial professional.
My most practical advice is to use the app with a written amount, a repayment date, and a comparison list prepared before submitting anything. If the numbers do not work on paper, they will not become safer because the application is convenient. If the terms are understandable and the payment fits comfortably within the next budget, the app may be a reasonable place to explore the option. If either point is uncertain, stopping is the wiser outcome.
In the end, Instant Cash Advance Loan App is best viewed as an occasional decision tool, not a permanent financial habit. It can save time during a stressful moment, but its lasting value depends on restraint, comparison, and a realistic repayment plan. For me, that makes it worth knowing about, while keeping it firmly outside the center of my everyday money routine.
FAQ
What is the Instant Cash Advance Loan App, and how does it work?
Instant Cash Advance Loan App is designed to let eligible users apply for a short-term personal loan directly from an Android or iOS device. After creating an account, you generally provide personal, employment, and banking information, choose an available loan amount, and submit an application for review. Approval, funding speed, and available terms depend on the lender, your location, credit profile, and the information you provide.
Is the Instant Cash Advance Loan App safe to use?
The app may use security measures such as account authentication, encrypted data transmission, and privacy controls, but users should still review its permissions and privacy policy before registering. Only download it from an official app store or verified lender website, and confirm the company’s identity and licensing. Never share passwords, verification codes, or banking details through unofficial messages claiming to represent the service.
How much does borrowing through the app cost?
The total cost can include interest, an origination fee, late-payment charges, subscription costs, or other lender-specific fees. The annual percentage rate may be significantly higher than rates offered by traditional banks, especially for short-term borrowing. Before accepting an offer, carefully check the repayment schedule, total amount due, automatic-payment conditions, and all applicable fees rather than focusing only on the advertised loan amount.
How quickly can I receive the money after approval?
Some applications may provide a lending decision within minutes and transfer approved funds quickly, but instant funding is not guaranteed. The timing can depend on identity verification, business hours, your bank, the lender’s review process, and whether you qualify for expedited delivery. Standard transfers may take longer, and the app should clearly explain any additional fee for faster funding before you accept.
What should I do if I cannot repay the advance on time?
Contact the lender through the official support options as soon as you realize repayment may be difficult. Ask whether an extension, revised payment arrangement, or hardship option is available, and request the terms in writing. Avoid taking another high-cost loan to cover the first one unless you fully understand the consequences. Missed payments may result in fees, collection activity, bank charges, or damage to your credit history.


